Imagine this scenario:
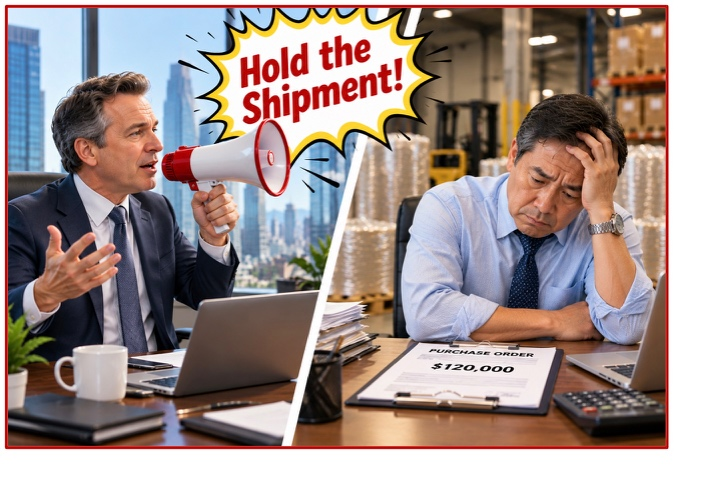
A long-term customer placed an order back in January for approximately $120,000 worth of product scheduled to ship in November. The product was manufactured specifically for the customer according to technical and compliance requirements.
Then, in June, the customer called with an unexpected request: “Please don’t ship it yet.”
Slowing demand, changing market conditions and the loss of several important customers had hurt the customer’s own business. They hoped conditions would improve and asked the supplier to hold the finished product until they were ready to take delivery.
The supplier agreed.
Unfortunately, as the months rolled by, the customer’s business didn’t appear to be improving. November was approaching, $120,000 worth of specially manufactured product was sitting in inventory, and the supplier was becoming increasingly concerned that the customer might never take it.
What would you do?
There isn’t necessarily one right answer, but before making a decision, here are several questions I would want answered.
What is the financial status of the customer today?
This is probably the most important place to start. A long-term relationship and good payment history are certainly valuable, but they don’t tell you what the customer’s financial condition looks like today.
If the relationship allows it, ask for current financial statements, an updated sales forecast and an explanation of what management expects over the next several months. The purpose isn’t simply to determine whether the customer can pay. You also want to understand whether the request to delay shipment represents a temporary setback or something potentially more serious.
Who ultimately uses the product?
Is the customer using the specialty product in its own manufacturing process, or is it purchasing the material for resale to other manufacturers?
If the product ultimately goes to the customer’s customers, there may be creative alternatives worth exploring. For example, could the supplier ship directly to an end user while preserving the original customer’s margin or other economic interest?
That won’t work in every situation, and any arrangement would have to be carefully documented and agreed upon by everyone involved. But understanding where the product ultimately goes may reveal options that aren’t obvious when you look only at the original purchase order.
Could extended payment terms solve the problem?
Suppose the customer still needs the product but simply doesn’t have the cash flow to accept and pay for the entire $120,000 shipment under the original terms.
Would shipping the product with a structured installment arrangement make sense?
Perhaps the customer could make an initial payment followed by monthly installments. Or the shipment could potentially be divided into smaller quantities, with each portion shipped and paid for according to an agreed schedule.
Extended terms obviously increase credit risk, so they shouldn’t be offered simply because everyone wants the problem to disappear. Any arrangement should be based on the customer’s financial condition and its realistic ability to perform.
Could someone else use the product?
This becomes especially important when goods have been manufactured to unique specifications.
Could another customer use the material as manufactured? Could it be modified or reformulated? Is there a secondary market for it?
The answer may be yes, but at what cost?
A technically possible solution isn’t necessarily an economically sensible one. If modifying a $120,000 product costs $40,000 and the resulting material can only be sold for $50,000, you haven’t necessarily solved much of the problem.
Understanding the product’s realistic resale value gives the supplier another important piece of information when negotiating with the original customer.
What is the product’s shelf life?
Time can dramatically change the negotiating position.
Suppose the product remains fully usable for approximately one year but begins losing important performance characteristics after that. If its salvage value eventually falls to only 20% of its production cost, every additional month that passes potentially increases the supplier’s exposure.
That creates an important distinction between being patient and simply postponing a loss.
The supplier should know exactly when the product begins losing commercial value and establish decision points well before reaching that date.
And perhaps the most important question: What does the contract say?
This is an area I would emphasize more strongly today than I did when I originally discussed situations like this.
Was the purchase order firm and noncancelable? When does title transfer? Does the agreement address specially manufactured goods, cancellation charges, storage costs, delayed delivery or the customer’s obligation to accept completed goods?
The commercial relationship matters, but so does the underlying contract.
Before agreeing indefinitely to “hold the shipment,” the supplier should understand what rights it may be giving up and what obligations the customer has already assumed.
Ultimately, situations like this rarely have a perfect solution.
The supplier may decide that preserving a valuable long-term relationship justifies some additional flexibility. But flexibility should have boundaries. Instead of leaving the shipment on hold indefinitely, the parties might establish specific dates for reviewing the customer’s financial condition, making partial payments, accepting portions of the shipment or reaching a final decision about the goods.
And that may be the biggest lesson of all.
“Hold the shipment” should never become “hold the shipment indefinitely.”
When specially manufactured goods are sitting in your warehouse, time isn’t standing still. The product may be aging, its resale options may be shrinking, and your credit exposure may be increasing.
Sometimes working with a struggling customer is absolutely the right thing to do.
Just make sure that while you’re giving the customer time, you aren’t allowing time to make the decision for you.
Your thoughts and comments (nseiverd@cmiweb.com) are most welcome!
Nancy Seiverd, President
CMI Credit Mediators, Inc.
All Rights Reserved
