For centuries, credit and collection professionals have encountered countless explanations for why an overdue invoice hasn’t been paid. But what happens when the person offering the explanation isn’t a person at all?
Welcome to the brave new world of artificial intelligence working in accounts payable.
Recently, a collection professional shared an experience that left her wondering whether AI was making the collection process more efficient or simply creating another obstacle between creditors and their money.
She had called a customer’s accounts payable manager regarding several past-due invoices. It was a routine collection call and one she had made countless times throughout her career.
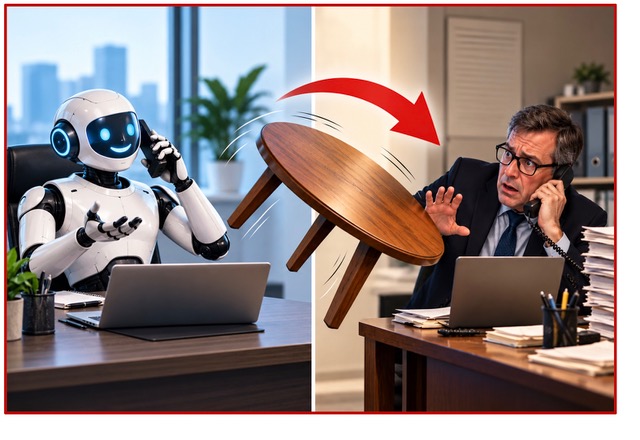
But this time, instead of reaching the manager or even a traditional voicemail system, she found herself speaking with an AI-powered virtual assistant.
At first, everything seemed perfectly reasonable.
The AI assistant politely requested the invoice numbers, invoice dates, due dates, outstanding amounts, and other identifying information. The collector patiently provided everything requested, believing that perhaps this technology might actually help expedite the payment process.
After gathering all the information, the AI assistant asked whether she had any additional questions or comments.
“Yes,” she replied. “When will payment be made?”
The response?
“The accounts payable manager will get back to you as soon as possible.”
And that was it!
After spending several minutes providing detailed information to a remarkably polite artificial intelligence system, she had accomplished essentially the same thing as leaving a lengthy voicemail.
No payment date. No commitment. No explanation for the delay. And certainly, no money.
A New Technology, an Old Frustration
For credit and collection professionals, this experience raises an interesting question: Is artificial intelligence improving communication between creditors and customers, or is it simply adding another layer of bureaucracy?
To be fair, AI has tremendous potential to improve accounts payable operations. Properly designed systems can help companies process invoices, identify discrepancies, reconcile accounts, and potentially provide creditors with real-time payment information.
Imagine calling a customer’s accounts payable department and having an AI assistant immediately confirm that an invoice has been approved for payment, identify the scheduled payment date, or explain why an invoice remains on hold.
That would represent genuine progress.
But an AI system that merely collects information and promises that someone will eventually respond offers little practical advantage over conventional voicemail.
When Does Efficiency Become Avoidance?
Credit professionals have long encountered customers who employ various tactics to delay payment. Sometimes the explanations are legitimate. Other times, familiar phrases such as “The check is in the mail,” “We’re waiting for approval,” or “The person responsible is unavailable” become frustratingly repetitive.
Could AI unintentionally become another version of these familiar delaying tactics?
Or could some companies eventually use automated systems to insulate their accounts payable personnel from persistent collection calls?
We shouldn’t automatically assume that this is happening. The customer in our example may have introduced AI simply to improve efficiency and reduce administrative workloads.
Nevertheless, the consequences for the creditor can be remarkably similar.
The Importance of Having a Direct Line
This experience also highlights something that credit managers should address long before an invoice becomes overdue: knowing how to reach the person responsible for payment.
In today’s business environment, when smartphones have become an indispensable part of daily life, having a direct telephone number, and preferably a business mobile number, for the accounts payable manager can be an invaluable collection tool.
That’s why obtaining this information should be an important part of the customer onboarding and credit application process.
Along with the usual company information, credit managers should request the name, email address, direct telephone number, and, where available, business mobile number of the person responsible for approving and processing payments. An alternate contact is equally valuable.
Of course, these contact details should be obtained with appropriate consent and used professionally for legitimate business purposes.
The objective isn’t to bypass established procedures or repeatedly call someone on their mobile phone. It’s to ensure that when an invoice becomes seriously overdue, the creditor has a reasonable means of reaching someone who can actually address the problem.
After all, the worst time to discover that you don’t have the right person’s telephone number is when your customer has already stopped paying.
The Human Element Still Matters
As AI becomes more prevalent, collection professionals may need to adjust their approach by establishing clear expectations regarding payment commitments, follow-up dates, and access to individuals authorized to resolve outstanding balances.
They should also document automated interactions and determine when an unresolved response warrants escalation to a credit manager or other decision-maker.
An overdue invoice doesn’t become less overdue simply because a computer has acknowledged its existence.
Technology should facilitate communication, not replace accountability.
A truly effective AI-powered accounts payable system should help creditors obtain meaningful answers, not simply provide a sophisticated method of recording their questions.
Perhaps the ultimate test of AI in accounts payable isn’t how intelligently it answers the telephone, but whether it helps resolve the financial obligations behind the call.
Because if AI can answer the phone but cannot answer the question of when payment will be made, perhaps we haven’t made the collection process more intelligent. We’ve simply made it more complicated.
Your thoughts and comments (nseiverd@cmiweb.com) are most welcome!
Nancy Seiverd, President
CMI Credit Mediators, Inc.
All Rights Reserved
