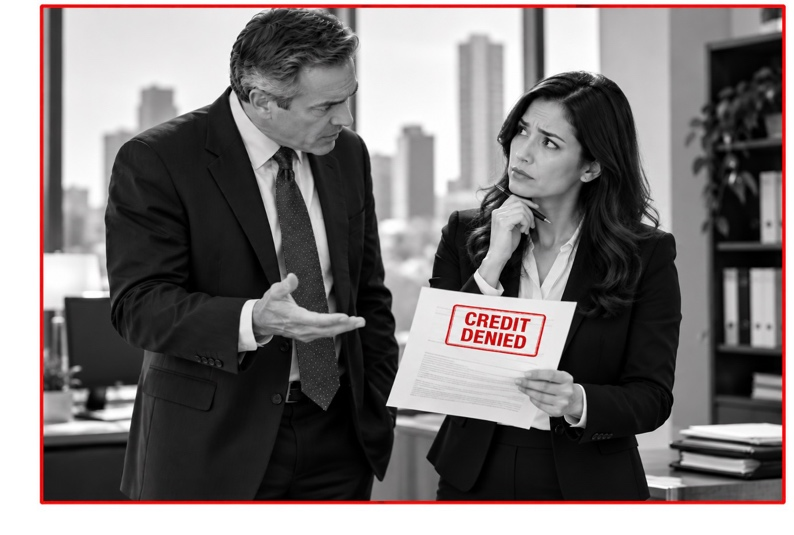
You are the credit manager for a mid-sized company, and the president asks you to establish a $100,000 credit line for a company owned by his brother-in-law.
As you conduct your normal credit investigation, what you uncover isn’t encouraging. Credit reports, trade references and other available information indicate a history of seriously delinquent payments and unpaid obligations. This isn’t a marginal credit risk where reasonable people might disagree. Everything you have found tells you that extending $100,000 in unsecured credit would be a very bad idea.
You document your findings and recommend declining the request.
The president responds, “He’s my brother-in-law. Approve it.”
On one hand, the president presumably has the authority to decide how much financial risk the company is willing to assume. As credit professionals, we analyze risk and make recommendations, but that doesn’t necessarily mean we have the final word.
If senior management decides to accept a risk after being fully informed of the potential consequences, one could argue that the credit professional has fulfilled his or her responsibility. Document the recommendation, obtain written authorization for the override and move forward.
But is this situation different?
The president isn’t necessarily overriding the credit decision because he has additional information about the customer’s financial condition or because there is a compelling business reason for accepting the risk. He is making an exception for a company owned by a close relative.
That raises another question: Would the president approve the same $100,000 credit line if the applicant weren’t his brother-in-law?
If the answer is no, the credit manager may begin wondering whether this is really a disagreement over credit policy or whether personal considerations are being allowed to override sound business judgment.
And that’s where the issue can become much more personal for the credit professional.
Being overruled occasionally is part of working in almost any organization. Credit managers shouldn’t expect every recommendation they make to become the final decision.
But what happens when an override appears so contrary to the available facts that it causes you to question management’s judgment?
Would you simply document your objection and accept that management has the authority to make the final decision? Would you push back harder? Would you insist that the president formally accept responsibility for the credit exposure?
Or would the decision cause you to question whether you wanted to continue working for the company at all?
For some credit professionals, resigning over one decision might seem extreme. Their position might be: I identified the risk, documented it and advised management. What management chooses to do with that information is ultimately management’s responsibility.
Others may see it differently. If their professional judgment can be disregarded when a personal relationship is involved, particularly when a substantial amount of money is at stake, they may wonder what purpose their role really serves.
There may not be one right answer.
But there is an important distinction worth considering:
Being overruled doesn’t necessarily undermine your professional integrity. Being expected to ignore what you know just might.
So, what would you do?
Your thoughts and comments (nseiverd@cmiweb.com) are most welcome!
Nancy Seiverd, President
CMI Credit Mediators, Inc.
All Rights Reserved
